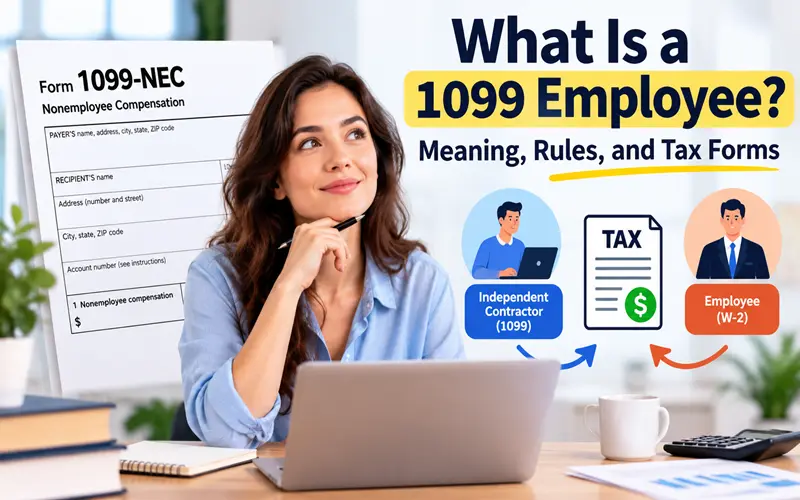
A 1099 employee is a colloquial term for an independent contractor, freelancer, or self-employed professional an enterprise retains to provide specific services under a commercial contract rather than an employment agreement (Internal Revenue Service [IRS], 2024b). Unlike traditional payroll staff, a 1099 employee receives gross compensation with zero federal or state tax withholdings, has their annual earnings reported on IRS Form 1099-NEC, and remains personally liable for federal income and self-employment taxes (IRS, 2024a, 2024c).
When finance leaders examine what a 1099 employee is, it is critical to recognize that the term is technically a legal contradiction (U.S. Department of Labor [DOL], 2024). Under federal regulatory standards enforced by the Internal Revenue Service and the U.S. Department of Labor, a worker is legally categorized either as a common-law W-2 employee or an independent business entity there is no hybrid classification under federal law (DOL, 2024; IRS, 2024b).
The foundational meaning of a 1099 employee is rooted in commercial independence: the worker operates as an autonomous business vendor delivering a contracted scope of work rather than functioning as an integrated member of a client company’s core workforce.
Key operational attributes of this classification include:
- Behavioral and Operational Autonomy: The contractor controls the processes, schedules, and specific methods used to fulfill project deliverables.
- Capital and Resource Investment: The contractor provides their own tooling, computer hardware, specialized software licenses, and workspaces.
- Commercial Profit and Loss Exposure: The individual can realize an enterprise profit or sustain an economic loss depending on fee structures, overhead, and operating expenses.
Form 1099-NEC: The Dedicated 1099 Employee Form
The primary 1099 employee form used for reporting nonemployee compensation to the federal government is IRS Form 1099-NEC.
Before tax year 2020, client businesses reported nonemployee compensation in Box 7 of Form 1099-MISC. The IRS reintroduced Form 1099-NEC as a standalone information return to separate independent contractor payments from miscellaneous income streams and satisfy statutory filing timelines established under the PATH Act.
Statutory Reporting Thresholds and Filing Deadlines
- The $600 Reporting Baseline: A business must issue the primary 1099 employee form Form 1099-NEC to any non-corporate independent contractor paid $600 or more in cumulative services, fees, or commissions during a calendar tax year in the course of trade or business.
- Form W-9 Verification: Before issuing any disbursements, organizations must obtain an executed Form W-9 (Request for Taxpayer Identification Number and Certification) to verify the payee’s legal business name, tax classification, and Taxpayer Identification Number (TIN or SSN) (IRS, 2024d).
- Statutory Filing Timeline: Under Internal Revenue Code § 6071(c), organizations must file Copy A of Form 1099-NEC with the IRS and furnish Copy B to the contractor on or before January 31 following the close of the reporting tax year.
- Mandatory Backup Withholding: If a contractor fails to furnish a certified TIN before payment, the hiring organization is statutorily required under IRC § 3406 to enforce backup withholding at a flat 24% rate and remit those funds directly to the IRS (IRS, 2024a, 2024d).
1099 Independent Contractor vs. W-2 Employee: Core Differences
The operational divide between a 1099 employee and a common-law employee dictates accounting procedures, benefits eligibility, and regulatory compliance exposure:
| Feature / Obligation | 1099 Independent Contractor | W-2 Common-Law Employee |
| Legal Status | Business-to-business vendor agreement | Common-law employment relationship |
| Annual Tax Documentation | Form 1099-NEC (1099 employee form) | Form W-2 (Wage and Tax Statement) |
| Payroll Tax Withholding | Exempt ($0 withheld by hiring firm) | Mandatory federal, state, and local payroll deductions |
| FICA / SECA Contributions | Contractor pays 15.3% SECA on net earnings | 15.3% split: 7.65% paid by employer, 7.65% paid by employee |
| Unemployment Taxes | Statutorily exempt from FUTA and SUTA | Mandatory employer contributions to FUTA and SUTA |
| Disbursement Workflow | Accounts Payable via vendor invoices | Payroll processing via wages or salaries |
| FLSA Protections | Statutorily exempt from minimum wage and overtime (DOL, 2024) | Covered under Fair Labor Standards Act provisions |
| ERISA Benefits Access | Ineligible for employer health and retirement plans | Eligible based on statutory thresholds and company policy |
| Operational Direction | Controls execution methods, tools, and schedule | Employer dictates schedule, processes, and equipment |
Legal Worker Classification Frameworks: DOL and IRS Tests
Worker classification cannot be established merely by private agreement, contract language, or job titles; regulatory agencies evaluate relationships using multi-factor statutory tests.
The DOL Six-Factor Economic Reality Test
Under the Fair Labor Standards Act (FLSA), the Department of Labor assesses whether a worker is economically dependent on the employer or operating an independent trade through six primary factors (DOL, 2024):
- Opportunity for profit or loss depending on managerial skill: Evaluates whether the worker negotiates rates, accepts or rejects assignments, and exercises business initiative.
- Investments by the worker and the employer: Compares the worker’s capital investments in equipment and software against the client organization’s investments.
- Degree of permanence of the work relationship: Distinguishes finite, milestone-driven projects from open-ended, continuous employment.
- Nature and degree of control: Examines who controls scheduling, supervision, pricing, and external client relationships.
- Extent to which the work performed is an integral part of the business: Evaluates whether the tasks represent a core operational deliverable of the hiring enterprise.
- Skill and initiative: Assesses whether the worker applies specialized expertise and independent commercial judgment rather than receiving company training.
State-Level ABC Standards (e.g., California AB 5)
Several jurisdictions enforce the stricter “ABC Test” under state labor codes and wage orders (State of California Department of Industrial Relations, 2024). Under this legal presumption, a worker is deemed an employee unless the hiring business proves all three conditions:
- Prong A: The worker is free from the control and direction of the hiring entity regarding the performance of work.
- Prong B: The worker performs work that is outside the usual course of the hiring entity’s business.
- Prong C: The worker is customarily engaged in an independently established trade, occupation, or business of the same nature as that involved in the work performed.
Read Also: $3000 IRS Tax Refund Schedule 2025: Who Qualifies and When to Expect Your Money
Can a 1099 Worker Log 40 Hours per Week?
Yes, an independent contractor may work 40 or more hours in a single workweek, provided the schedule reflects project volume rather than employer-mandated working hours.
- Deliverable Deadlines vs. Schedule Directives: A client company may establish milestone delivery targets. However, mandating fixed work shifts such as requiring a contractor to work from 9:00 AM to 5:00 PM daily exercises behavioral control under IRS guidelines and increases reclassification risk.
- FLSA Overtime Exemption: Legitimate independent contractors are statutorily exempt from FLSA overtime protections and are not entitled to time-and-a-half premium pay for hours worked beyond 40 in a calendar week.
Statutory Penalties for Misclassifying 1099 Workers
Misclassifying common-law employees as independent contractors exposes enterprises to significant retroactive assessments and statutory penalties under Internal Revenue Code § 3509 :
- Unfiled Information Return Assessments: Statutory penalties apply for each unfiled Form W-2 under IRC § 6721.
- Retroactive Federal Income Tax Withholding: Under IRC § 3509(a)(1), the employer is assessed 1.5% of gross wages paid, which doubles to 3.0% under IRC § 3509(b)(1) if the business failed to file Form 1099-NEC.
- Retroactive Employee FICA Recovery: Under IRC § 3509(a)(2), the employer is assessed 20% of the employee’s unwithheld FICA share, increasing to 40% under IRC § 3509(b)(2) if Form 1099-NEC was omitted.
- Employer Matching Obligations: The enterprise remains liable for 100% of the employer’s matching FICA share (7.65%) along with retroactive Federal (FUTA) and State (SUTA) Unemployment Tax Act contributions.
- Revocation of Relief for Willful Non-Compliance: Statutory mitigation under IRC § 3509 is unavailable in cases involving intentional disregard or willful misclassification, leaving the enterprise liable for full income tax withholdings, the complete 15.3% FICA obligation, compounding statutory interest, and potential criminal sanctions under IRC § 7202.
Tax Liabilities for the 1099 Worker: SECA and Deductions
Because client organizations remit gross compensation without payroll subtractions, independent contractors manage their own tax liabilities and quarterly reporting.
Self-Employment Tax (SECA)
Under the Self-Employment Contributions Act, independent contractors fund both the employer and employee shares of Social Security and Medicare :
- Statutory SECA Rate: The SECA tax rate is 15.3% on net earnings, comprising 12.4% for Social Security up to the annual statutory wage limit and 2.9% for Medicare, plus an additional 0.9% surtax for higher-income brackets.
- Adjusted Gross Income Deduction: Contractors can deduct 50% of their total SECA tax liability from adjusted gross income on IRS Form 1040 (Schedule 1).
Quarterly Estimated Tax Payments
Contractors expecting to owe $1,000 or more in annual federal taxes must make quarterly estimated payments using IRS Form 1040-ES across four statutory due dates: April 15, June 15, September 15, and January 15 of the following year.
Deductible Business Expenses
Independent professionals can deduct ordinary and necessary business expenses under IRC § 162 on IRS Schedule C to lower their net business income, including:
- Dedicated home office expenses calculated under the simplified or actual expense methods.
- Hardware, specialized equipment, and operational software subscriptions.
- Professional liability coverage and qualifying self-employed health insurance premiums.
- Documented travel and mileage incurred exclusively for business operations.
Operational Decision Framework: 1099 Contractor vs. W-2 Employee
Finance and human resource leaders should evaluate workforce requirements using this baseline operational framework:
When to Engage an Independent Contractor:
- Specialized, Milestone-Driven Initiatives: The engagement requires niche expertise for a finite duration (e.g., enterprise system deployments, external audits, or interim strategy consulting).
- Deliverable-Focused Management: The organization evaluates the end product rather than supervising daily workflows or processes.
- Independent Tooling: The individual uses their own hardware, specialized software licenses, and working facilities.
When to Hire a W-2 Employee:
- Core Business Operations: The responsibilities are continuous and central to the organization’s primary revenue generation.
- Direct Process Control: Leadership requires authority over working hours, procedures, and continuous internal oversight.
- Indefinite Engagement: The company expects an ongoing, indefinite relationship and restricts the individual from serving commercial competitors.
Frequently Asked Questions
A 1099 employee is an independent contractor or vendor contracted to perform specific work for a client organization. The client pays gross compensation without tax withholdings, reports the payments on Form 1099-NEC, and does not provide employee benefits.
The 1099 employee meaning reflects that the client business has zero payroll tax withholding obligations for the engagement. The contractor pays the full 15.3% Self-Employment Contributions Act (SECA) tax on their net business earnings and makes quarterly estimated payments for federal and state income taxes.
The primary 1099 employee form is IRS Form 1099-NEC (Nonemployee Compensation). A business must file this form with the IRS and provide a copy to the contractor by January 31 if total compensation paid to an unincorporated contractor reaches or exceeds $600 during the calendar tax year.
No. Independent contractors are statutorily exempt from the Fair Labor Standards Act (FLSA). They do not qualify for federal minimum wage protections or overtime pay for hours exceeding 40 per week; compensation is determined entirely by the terms of the commercial contract.